Canada's Clean Fuel Regulations (CFR) have created a genuine national market for low-carbon fuel credits. Turning that market into revenue is still harder than it looks.
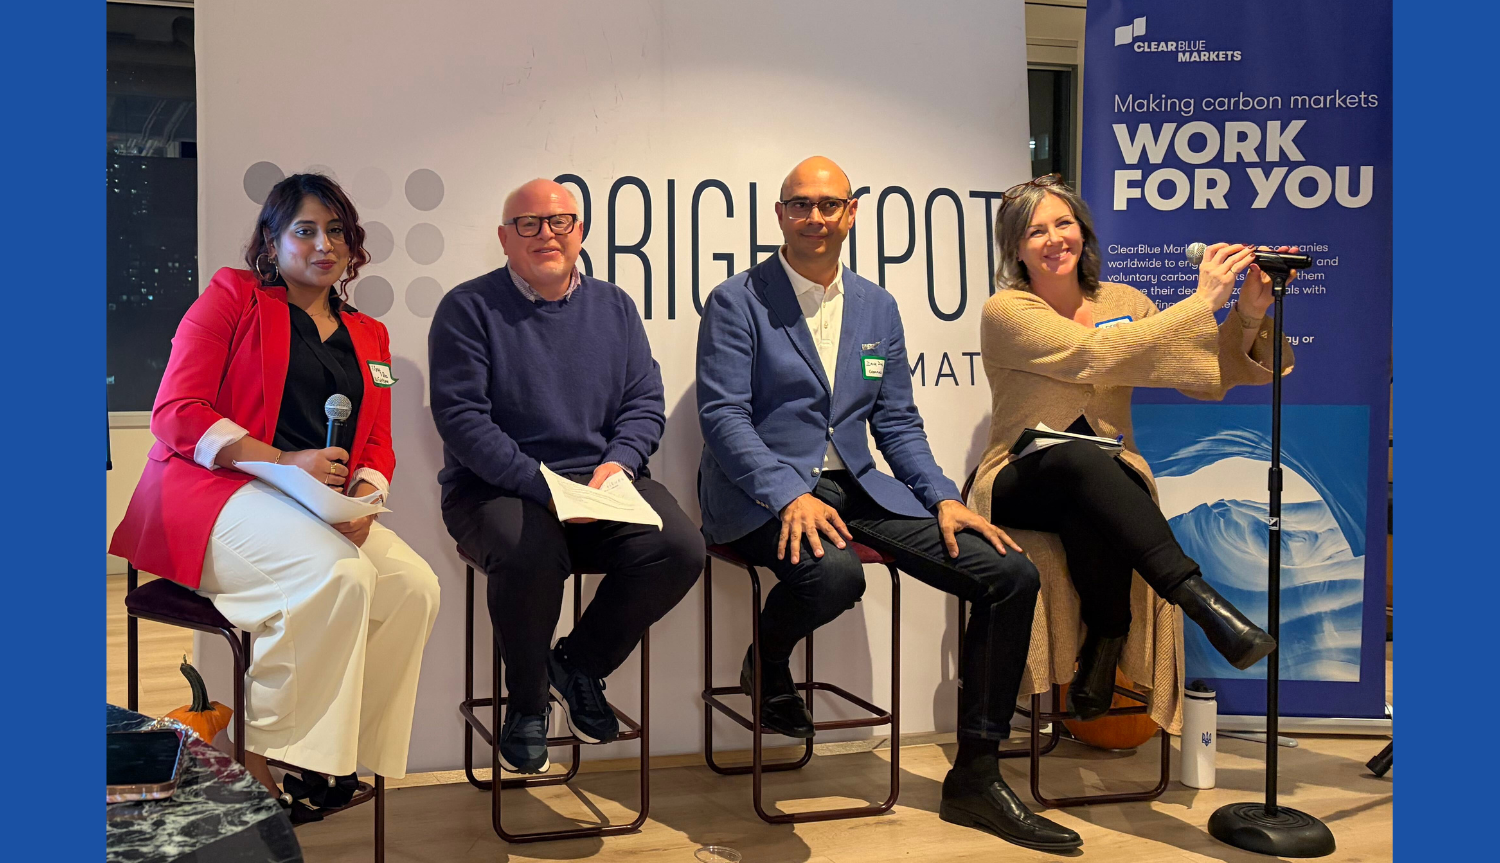
That was the message from the October 15 edition of the Toronto Carbon Club, co-hosted by ClearBlue Markets and Brightspot Climate. Moderated by Fiona D'Silva, Consultant at Brightspot Climate, the panel followed a low-carbon fuel project from business case to credit revenue through three lenses:
- Douglas Dias, Executive Vice President & Co-Managing Director, Renewable Energy – Commercial, Greenfield Global, on producing and supplying the fuel
- Lorena Ellsworth, Principal, Brightspot Climate, on quantifying and verifying carbon intensity
- Michael Berends, CEO & Co-founder, ClearBlue Markets, on carbon markets, pricing and risk management
Here are the key takeaways.
A national carbon market that works, and goes beyond fuel
For anyone who has worked through Canada's patchwork of provincial carbon programs, the CFR is a milestone. Michael Berends opened by calling it the first truly pan-Canadian carbon market.
"If you take a step back, the CFR is the first truly Canada-wide carbon market, and it's working. You finally have clients seeing one price for their credits or their obligation across Canada." — Michael Berends, CEO & Co-founder, ClearBlue Markets
The opportunity reaches well past liquid fuels. Michael pointed to electric vehicle charging, from fleet vehicles to the forklifts and golf carts in logistics warehouses, as a fast-growing source of credits. ClearBlue fields questions about EV credit generation roughly once a week. He also flagged biogas produced and used on site by larger industrial players, such as food processors, as a significant and often overlooked opportunity.
Where a project is built changes whether it pencils out
Doug Dias welcomed the clarity the CFR's carbon intensity (CI) score has brought. Biofuels are now judged on lifecycle performance rather than volume alone. But he argued the regulation is currently working best for U.S. producers.
"The CFR has created demand for these products, but it hasn't necessarily created demand for domestic sources of them." — Douglas Dias, EVP & Co-Managing Director, Renewable Energy – Commercial, Greenfield Global
He illustrated the point with two projects. At Greenfield's ethanol plant on Montreal's south shore, replacing a natural gas boiler with an electric one will cut the plant's CI score by about 10 grams. That works even though electricity costs nearly three times as much as natural gas at the burner tip, because CFR credits, Quebec's own CI requirement and provincial decarbonization grants close the gap. The same project in Ontario faces roughly a sixfold power cost disadvantage and no comparable capital support, so it doesn't proceed.
Doug also noted that a U.S. plant just south of the border could earn about 50 cents a gallon in 45Z tax credits on top of the same CFR value. That leaves Canadian producers competing against a significant subsidy.
Credits are only as good as the data behind them
CFR credits aren't automatic. Every carbon intensity claim goes through verification, and Lorena Ellsworth was emphatic about what makes a project stand up to it.
"I'm going to sound like a broken record: data quality, data quality, data quality. Your data needs to be traceable. Your verifier has to understand where everything is coming from." — Lorena Ellsworth, Principal, Brightspot Climate
She walked through how long the process takes. A CI application typically follows within six months of the end of a reporting period, and verification takes another two to three months. Even then, Environment and Climate Change Canada (ECCC) still has to approve and assign the CI. Annual reporting follows, covering carbon intensity pathways, fuel and feedstock quantities, material balance, and credit adjustment or creation reports. Brightspot is one of only 16 accredited CFR verifiers.
For biogas and RNG projects, she noted that avoided emissions and digestate storage can drive most of a project's CI, which makes them the place to focus both operational improvements and documentation. Doug added a producer's view: for large investments, he'd like to see something like Europe's pre-certification, which validates a pathway before a final investment decision is made.
What to watch over the next two to three years
The targeted amendments. More than a year after they were announced, the federal government's targeted CFR amendments still haven't been published. They are expected to include a credit multiplier for Canadian producers and possibly a domestic content requirement. Doug argued the delay has made the sector less investable, the opposite of the amendments' intent. He credited domestic content rules in British Columbia and Ontario with keeping a Canadian industry alive, and noted that Canada's ethanol supply has flipped from roughly 70% domestic to 70% imported in three or four years.
Multipliers have trade-offs. Michael cautioned that a multiplier adds credit volume to the market, which lowers the value of credits for other generators, including EV charging operators. Policy-makers will need to weigh every lever.
Approval timelines. Michael said some clients are sitting on millions of dollars in credits while they wait for CI approvals. He also pointed out that the regulations are new, and some areas are still being clarified, such as new biogas pathways and some EV charging setups, where greater shared understanding will help more projects move forward with confidence. Lorena said ECCC is clearly working to build its knowledge and called for simpler regulations.
Credit longevity. Asked how long a project can count on generating credits, Michael's answer was: likely as long as the regulation stands. The longer the program continues, the more investment flows into projects that create credits, and no one wants those projects to lose their value in the future. That includes many obligated parties, who are themselves investing in credit-generating projects.
The bottom line
As Fiona put it in closing, the room loves the CFR, and the CFR also keeps us up at night. The market is real and the demand is there. Capturing the value takes careful project siting, verification-ready data from day one, and close attention to policy that is still taking shape.
Thank you to our panelists and to everyone who joined us. ClearBlue Markets tracks CFR credit prices, supply and demand, and policy developments through its Vantage platform. Get in touch to talk about what the CFR means for your projects or compliance strategy.
